Solutions

Greater assertiveness in granting credit. More sales, fewer defaults.

A layer of adaptive intelligence for your company’s existing credit operations. Greater accuracy, more sales, and fewer delinquencies.

Contact Sales

  • Compliance with the LGPD
  • BCB Resolution No. 85/2021
  • ISO/ISE 27001:2022 Certification

How most credit operations make decisions

Most companies that take on credit risk—financial institutions, credit unions, fintech companies, digital banks, payment providers, or retailers with their own financial operations—make credit decisions based on a combination of credit bureau scores and manual review. Simple rules filter out the most obvious cases right at the outset—the so-called “high-risk” cases.

Next, the credit score—whether from a credit bureau or a proprietary model—makes the next selection. Finally, a team of analysts steps in for cases that the scoring model cannot decide with certainty. The credit bureau’s scoring model accounts for most of the market’s delinquencies and fulfills this role well: it provides a view of the entire market. However, it was trained on the general population, not on each creditor’s specific database, so it does not, on its own, capture the behavior of the niche associated with each transaction.

This has two effects at the same time: good payers are rejected, and bad payers are approved without the model realizing it.

That is why the 4kst Customized Credit Score does not seek to replace the credit bureau, but rather to supplement it with exactly what the bureau cannot see on its own: the client’s own portfolio, risk appetite, and the specific behavior of that business.

Manual analysis compensates for some of this inaccuracy, but at the cost of rising fixed costs and a decision-making process that can cost the sale. And even when a company moves to its own customized model, the challenge simply takes on a different form—it doesn’t disappear: every static model becomes outdated as soon as it goes into production, and recalibration takes weeks or months.

Three data sources

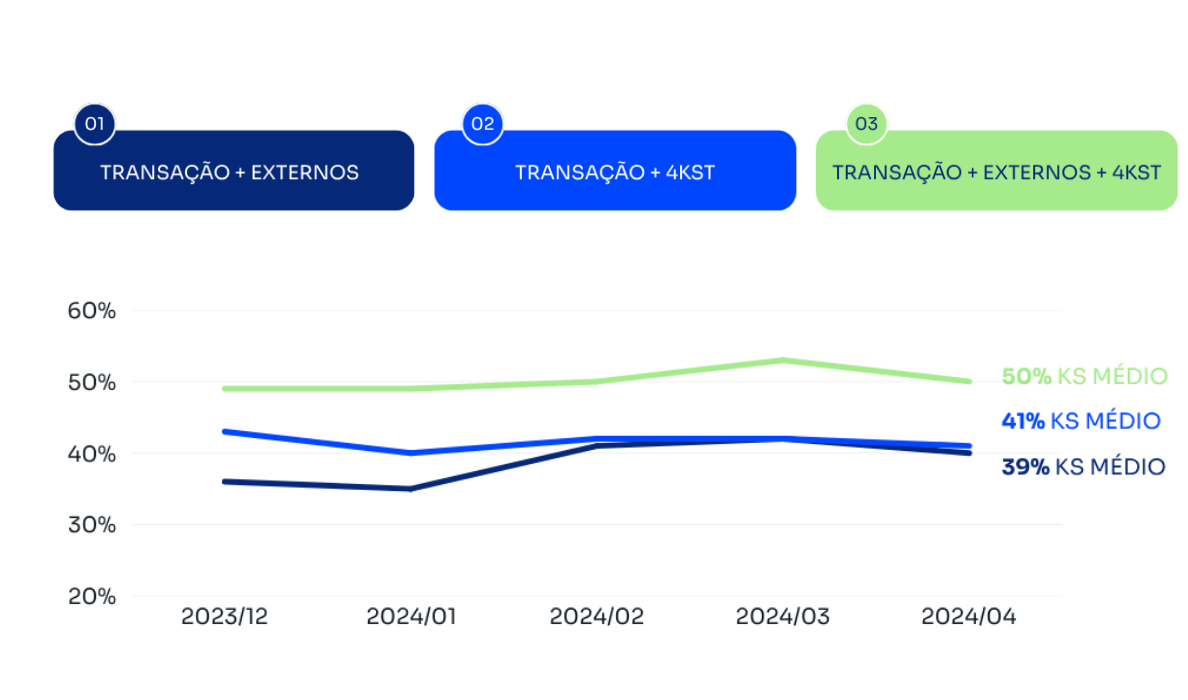
  • Transaction details: amount, date, interest rate, installment amount, and internal transaction history.
  • Credit bureau data: credit score, estimated income/revenue, credit restrictions, and other variables available from the credit bureau you use.
  • 4kst proprietary data: more than 260 attributes for individuals and legal entities, exclusive to the 4kst database.

Credit model with three possible configurations

These three sources can be combined in three possible configurations, defined in collaboration with the 4kst team based on the design of your operation:

1. With a bureau: improved accuracy at no additional data cost.

2. No agency: cost savings on external data.

3. All data: maximum possible performance.

Have you seen what the adaptive intelligence layer does for assertiveness?

Run a backtest using your data and see how it can improve your credit operations.

Talk to an expert

Logo

Benefits

An additional layer of adaptive intelligence for credit operations.

More sales, fewer defaults

By increasing assertiveness, it is possible to approve more applicants while maintaining the same level of risk and reduce delinquency while maintaining the same volume.

Lower operating costs

Automatic approval in milliseconds, with 100% compliance with the credit policy established by management.

Adaptive Credit Model

Adaptive AI 4kst technology learns continuously. There are no obsolescence windows, and no manual recalibration is required.

Custom Configuration

Three options suited to different contexts, developed jointly by the 4kst team and the client.

Ongoing monitoring

Model stability monitoring and analytical refinement. In a real-world case, the team identified a risk deviation as early as the first week.

Calculable ROI

It is based on actual data from the client's operations; it is not a generic estimate.

Logo


's Achievements

55%

greater assertiveness regarding the credit bureau used by a large retail chain

60%

unless a telecommunications company defaults

26%

increase in total revenue (illustrative impact in a real-world scenario)

+70M

backed transactions per year in less than 1 second

Testimonials from those who have chosen 4kst

Real testimonials from customers who transformed their results with the 4kst Customized Credit Score.

Questions? We'll solve them

Here you'll find quick answers to the most common questions.

No. The credit bureau score is still queried as usual and is included as one of the variables in the model. The 4kst Customized Credit Score adds to this the data from the transaction itself and more than 260 proprietary 4kst attributes.

The model runs on the 4kst cloud and connects to the customer's system via API, without a dedicated interface, login, or installation. It is consumed as a service (MLaaS), with recurring monthly billing based on call volume.

Neither. The conveyor belt is the entire credit-granting process, and the engine is the platform that orchestrates it. The 4kst Customized Credit Score is the predictive model that runs within the conveyor belt and the engine that the customer already uses.

Yes. Adaptive AI 4kst technology continuously learns from the actual flow of validated data from the customer’s operations, without the need for manual retraining and without losing accuracy over time, within a secure, encrypted environment that prevents data contamination between customers.

The estimated timeframe, from model development to production, is 6 to 8 weeks. The process involves scope alignment, model development, and presentation of the backtest before any major investment decision is made.

That analysis is the role of the 4kst Behavior Score, not this product. The 4kst Customized Credit Score is used in the origination process to analyze new customers prior to credit approval.

The model is integrated via API, with an SLA response time measured in milliseconds, cloud-native architecture, and encryption protocols. Your operational data is used exclusively for your model, without any cross-contamination with data from other customers, in compliance with LGPD requirements. 4kst does not replace your Data Science team; rather, it solves the problem of continuous updating that your team cannot address on its own.

The model’s terms are negotiated with the sales team based on the volume and complexity of the transaction, including models with a success fee. The recurring fee is charged based on call volume and adjusted according to actual usage.

Starting at 5,000 analyses per month, the Adaptive AI 4kst technology already has sufficient data flow to learn continuously. Below that threshold, evaluations are conducted on a case-by-case basis.

Customer data is used exclusively for that customer's model, in an encrypted environment, with no cross-contamination between customers.

More sales.
Fewer delinquencies.

Talk to our team and see how the 4kst Customized Credit Score would perform using your business's actual data.

  • Compliance with the LGPD
  • BCB Resolution No. 85/2021
  • ISO/ISE 27001:2022 Certification